Summary
Paying for senior living without selling a house is possible through rental income, home equity options, and other creative financing strategies. Families can explore multiple funding sources to preserve the family home while covering community costs.
- Rental income from the property can generate monthly funds to help pay for senior living expenses, though property taxes, maintenance, and management fees must be factored into calculations
- Home equity lines of credit and reverse mortgages allow access to home value without immediate sale, though each has specific eligibility requirements and conditions
- Bridge loans provide temporary financing for initial community costs while families decide on long-term property options, though they typically carry higher interest rates
- Retirement accounts, investment portfolios, Social Security, pensions, and life insurance benefits can be combined to support monthly expenses
- Medicaid may help eligible individuals with certain long-term services, but generally doesn't cover independent living or standard room-and-board costs; consult an attorney to understand Florida-specific rules
Moving a parent into senior living can raise an important financial question: Does the family house need to be sold to cover the costs?
Fortunately, paying for senior living without selling a house may be possible through rental income, existing savings, or other financing arrangements. Exploring these options gives families time to make thoughtful decisions without rushing to sell a property that holds years of memories. Understanding the alternatives can help you balance your parents' financial needs with their wishes for the family home.
Using Home Equity Without an Immediate Sale
Home equity can provide access to funds without requiring an immediate property sale. However, different financing arrangements come with important conditions.
Reverse Mortgages
A reverse mortgage for senior living costs allows eligible homeowners aged 62 or older to access a portion of their home's equity. However, most reverse mortgages require the borrower to occupy the property as their primary residence. Permanently moving into a senior living community may trigger repayment requirements.
This makes reverse mortgages more suitable for certain situations, such as when one spouse continues living in the house.
Home Equity Lines of Credit
A home equity line of credit (HELOC) allows homeowners to borrow against available equity. Unlike a reverse mortgage, a HELOC generally requires monthly payments. Interest rates may also fluctuate, affecting borrowing costs.
Before using either option, consult a qualified financial professional to understand eligibility, repayment obligations, and long-term implications.
Generating Income by Renting the Property
Renting a parent's house for care costs can create monthly income while allowing the family to retain ownership. This approach may work particularly well when the property is in good condition and located in an area with consistent rental demand.
Hiring a property manager can simplify tenant screening, rent collection, and maintenance coordination.
Before renting, account for expenses such as:
- Property taxes and insurance: Ongoing ownership expenses that continue after tenants move in.
- Maintenance and repairs: Routine upkeep and unexpected property expenses.
- Property management fees: Costs associated with hiring professionals to oversee the rental.
- Vacancy periods: Months when rental income may be unavailable.
Compare the property's expected net rental income with your parents' monthly senior living expenses.
For families considering Aston Gardens at Parkland Commons, understanding the monthly costs of Active Independent Living or Assisted Living can help determine how much rental income would be needed.
Exploring Bridge Loans and Short-Term Financing
Bridge loans for senior living provide temporary financing when families need funds before completing a property sale or accessing another financial resource.
These loans can help cover initial community expenses while allowing more time to make property decisions. However, bridge financing often carries higher interest rates and additional fees compared with traditional borrowing.
Families should consider:
- Repayment terms: When the loan must be repaid and whether extensions are available.
- Interest and fees: The total borrowing cost, including origination charges.
- Collateral requirements: Whether the family house or other assets secure the loan.
- Repayment strategy: How the balance will be paid if the property remains unsold.
Bridge financing may provide short-term flexibility, but it isn't necessarily a permanent solution. Reviewing the terms with a financial advisor can help families avoid unexpected financial pressure.
Using Investments, Retirement Income, and Insurance
Several senior living payment options besides a home sale involve resources families may already have. Retirement income, savings, and investment accounts can sometimes cover part or all of monthly community expenses.
Potential funding sources include:
- Retirement accounts: Withdrawals from IRAs, 401(k)s, and other qualified accounts.
- Investment portfolios: Funds from brokerage accounts or other investments.
- Pensions and Social Security: Recurring income that can contribute toward monthly expenses.
- Life insurance: Eligible policies with accessible cash value or other available benefits.
Each option has different financial implications. Retirement withdrawals may create taxable income, while accessing life insurance benefits can reduce the amount available to beneficiaries.
A financial planner can help determine which combination of resources best supports your parents' circumstances.
Understanding Medicaid and Financial Assistance
For families keeping a house while paying for assisted living, understanding available financial assistance is another important step.
Florida Medicaid programs may help eligible individuals access certain long-term services, depending on financial qualifications, assessed needs, and participating providers. However, Medicaid generally does not cover ordinary independent living expenses or standard room-and-board charges in assisted living.
Homeownership can also affect eligibility and estate recovery considerations. Consulting a Florida elder law attorney can help families understand applicable rules before transferring property or restructuring assets.
Families should confirm payment arrangements directly with any community they are considering rather than assuming government benefits will cover monthly charges.
Coordinating Multiple Funding Sources
Many families find that combining several resources provides greater flexibility than relying on one payment method. For example, rental income might contribute toward monthly expenses while retirement benefits cover the remaining balance.
When comparing communities, request a clear breakdown of housing costs, included amenities, and additional services.
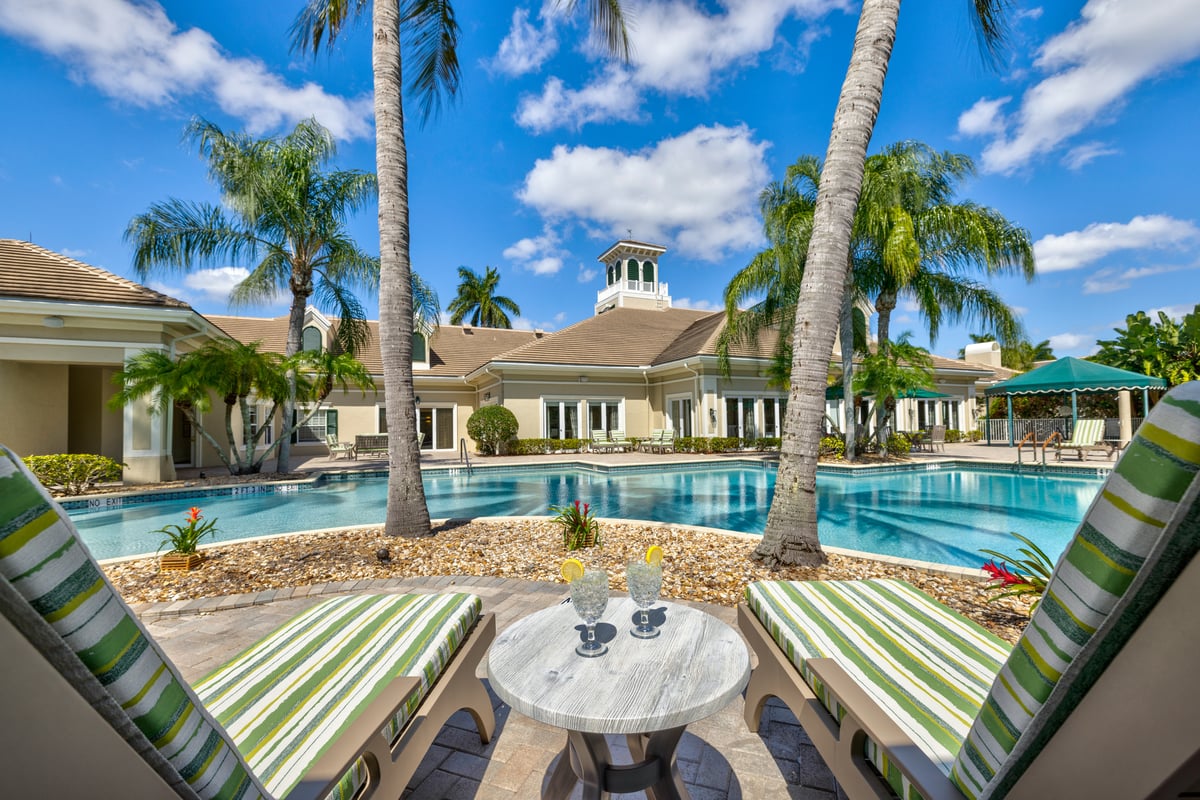
At Aston Gardens Parkland Commons, residents can enjoy community amenities such as Sensations dining, Celebrations programming, and Dimensions Health & Fitness. Understanding which services are included can help families develop a realistic monthly budget.
Explore Senior Living Options at Aston Gardens Parkland Commons
Paying for senior living without selling your parents' house requires thoughtful planning, but options such as rental income, savings, and financing may help preserve the property. Aston Gardens Parkland Commons offers Active Independent Living, Assisted Living, and specialized Memory Care, along with dining, wellness, and social programs that can help families evaluate the overall value of community living.
Schedule a tour of Aston Gardens Parkland Commons to explore the living options, learn about available amenities, and discuss pricing as you plan your family's next steps.